If you want to make sense of the unfolding story of real estate in Sacramento, be sure to keep an eye on inventory and interest rates. Take a minute to look over the graphs below to glean some context for how the market is evolving. Then let’s consider some thoughts further down.


Four thoughts on inventory and interest rates:
- Sweet Spot: Rates under 4% are a sweet spot for buyers. What do I mean? Buying was very aggressive in Sacramento when interest rates were below 4% for 19 months in a row. When rates increased above 4% in June 2013 from 3.5% in May, there was definitely an impact as inventory began to increase. Of course cash investors started exiting the market around that time too, which is also a big part of this trend.
- 40 Year Context: Some buyers need convincing to jump into the real estate game instead of waiting for rates to decline. Unless The Fed changes its bond buying patterns (which can lower rates), higher rates are expected to ensue. Think about the context though. Over the past 40 years interest rates have literally only been below 5% since 2008. In other words, we are spoiled with cheap money (even now) compared to everyone in decades past.
- Economics 101 for the Long-Term: If rates and inventory continue to rise, it will have a cooling impact on values over the long haul. This is particularly true since cash buyers are not around like they were last year to absorb inventory and create more competition for the rest of the market.
- Short-Term Economics: For the immediate market, interest rates are still incredibly low and inventory is still very low. This means there is room for upward value movement. Or in other words, demand is still outweighing supply. Last month saw less than 950 sales, but keep in mind January is always slow. The key point for me is that at the end of the month there were over 2000 pending sales that had not closed yet. This shows that buyers are hungry for real estate (I’ll share a graph about this on Tuesday). Right now inventory is still hovering around 2.5 months, so there will be very decent competition to get into contract in coming time. It won’t be the blood bath of 2013 when there was only one month of housing supply, but 2.5 months is not that much to work with for real estate Spring fever.
Questions: Any thoughts or questions? What are you seeing out there in the trenches of the market? Feel free to comment below.
If you liked this post, subscribe by email (or RSS). Thanks for being here.
 If you ever plan to get a tattoo on your face, call me first. That’s what I tell my two sons. They always roll their eyes and laugh at me when I say this. Of course I’m joking in part because they’re only 8 and 10 years old. But there is still a truth here nonetheless. It’s a good idea to get an outside perspective before making a big decision. There is something about consulting with a friend, family member, professional or even Facebook contacts to help weigh a decision and understand what to do. The same holds true in real estate when it comes to grasping the way the market is moving. When we dig into several different trends instead of just one, we tend to get a more balanced or holistic view of real estate. What do you see in the graphs below?


 The honeymoon is over. That’s right. The real estate market in 2013 felt like a honeymoon because it was full of glittery optimism, sensational news headlines and the sweet aroma of a quick recovery. Just as a honeymoon in real life comes to an end, we all knew such rapid appreciation was not sustainable, inventory could not be that low forever and interest rates wouldn’t endlessly hover at historically low levels either. Of course this doesn’t mean the market is not still ripe for positive growth, but only that this year probably won’t feel as good as last year.
 Housing inventory decreased last month below 2 months of supply, which is understandable in light of the holidays and colder weather. Otherwise inventory has been flirting with 2.5 months. I said above that the real estate “honeymoon” is over, but keep in mind inventory is still very low, which means there is still room for some growth ahead (though I do not believe we will see the same rapid appreciation like we did last year since the market is different this time around in terms of inventory, interest rates and cash investors). The median price in December saw a slight uptick from November, but overall is still hovering around the $250,000 range as it has been for about six months. Can you see why people are saying the market is flat?
 Here is a broader picture of median price and inventory. Current values are tending to resemble values in both 2003 and 2007/2008.
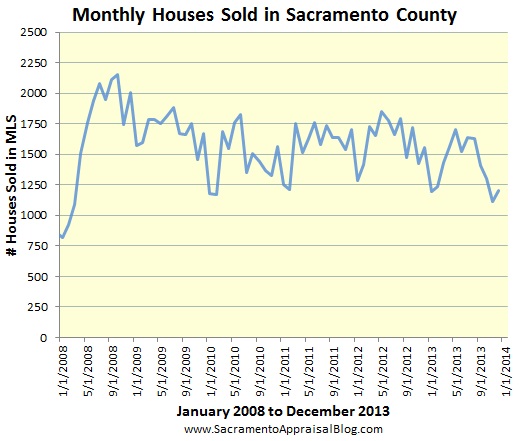 Sales were sparse for the

 The jobless rate is thankfully going down in Sacramento County, but 8.1% is still not a pretty statistic. Can I be a resounding gong by saying we need more JOBS, JOBS & JOBS?


