Let’s do a quick recap of how real estate unfolded in February in Sacramento County. There are two ways to read this post: 1) Briefly scan the graphs below in 30-ish seconds; or 2) Take a few minutes to digest the graphs and commentary.

Sluggish Sales: It’s normal for there to be less sales during colder months, though overall the market has felt sluggish. That’s my take and many real estate agents have also been talking about how the market has seemed to lag since the beginning of the year (though conversations are beginning to discuss the market heating up for Spring).

Similar to January: Sales were fairly similar to January in that there were only about 950 sales (single family detached). This number will go up slightly in coming days as more sales are reported, but it’s strong enough now to say this past month was fairly similar to the previous month in regards to sales volume.

Median Price Increase: The real estate market bottomed out in early 2012 after many years of decline, and the graph above charts the market rebound. The median price since January 2012 has risen from $160,000 to $259,000 and last month saw an increase from $240,000 to $259,000. Technically we could talk about how real estate increased by 8% last month, but sales volume has been REALLY low, which makes the median price weak since there aren’t as many sales to pack into the data set. So take this huge increase with a grain of salt. We could also say the median price has not been at $259,000 for six years either, but let’s try to avoid sensationalism based on one month of data during a Winter season that had VERY few sales.

Story of Inventory: Inventory is now at 2.5 months, which means on a monthly basis there are enough listings to satisfy two-and-a-half months worth of buyers. This is still a low figure, which leaves some room for very decent competition (but not the blood bath of last year when inventory was at one month). Keep in mind there are about 2300 pending listings right now too, which is a huge number. Some of these pending sales will of course fall out of contract, but many should close to help boost an increase of sales in March (which is the norm in Sacramento County).

Interest Rates Dipped: Interest rates saw a slight decline from January. When rates began to increase between May and June last year, it really impacted the real estate market and definitely helped to cool off values (investors began pulling back around the same time too). The market is definitely sensitive to the direction of interest rates and inventory in particular, so it’s important to watch trends carefully and consider the implications for the future.


Layers Working Together: I know I am constantly talking about the layers of the real estate market. I don’t mean to beat a dead horse, but watching how trends are unfolding together can help give us clues into how the market may unfold in coming time.

Some Context: If you’re looking for context for price levels, current values are similar to what they were during the first quarter in 2008 and toward the last quarter of 2003. Of course this is for the entire county and specific neighborhoods can vary greatly. Classic neighborhoods tend to be ahead of county numbers and the condo market tends to lag behind county numbers.
If this was helpful for you, please forward it to others.
Share the Graphs: As always, you can use these images unaltered in your newsletter, on social media sites or blog posts (just link back). See my sharing policy for more details about 5 different ways to share my content. Or if you need a quote for a blog post you’re writing, let me know.
Question: What are you seeing out there in the market? Do you sense Spring fever beginning to kick in or does it seem like the market is still lagging?
If you liked this post, subscribe by email (or RSS). Thanks for being here.


 The honeymoon is over. That’s right. The real estate market in 2013 felt like a honeymoon because it was full of glittery optimism, sensational news headlines and the sweet aroma of a quick recovery. Just as a honeymoon in real life comes to an end, we all knew such rapid appreciation was not sustainable, inventory could not be that low forever and interest rates wouldn’t endlessly hover at historically low levels either. Of course this doesn’t mean the market is not still ripe for positive growth, but only that this year probably won’t feel as good as last year.
 Housing inventory decreased last month below 2 months of supply, which is understandable in light of the holidays and colder weather. Otherwise inventory has been flirting with 2.5 months. I said above that the real estate “honeymoon” is over, but keep in mind inventory is still very low, which means there is still room for some growth ahead (though I do not believe we will see the same rapid appreciation like we did last year since the market is different this time around in terms of inventory, interest rates and cash investors). The median price in December saw a slight uptick from November, but overall is still hovering around the $250,000 range as it has been for about six months. Can you see why people are saying the market is flat?
 Here is a broader picture of median price and inventory. Current values are tending to resemble values in both 2003 and 2007/2008.
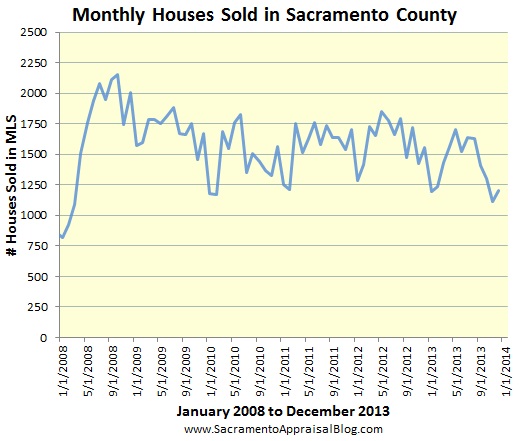 Sales were sparse for the

 The jobless rate is thankfully going down in Sacramento County, but 8.1% is still not a pretty statistic. Can I be a resounding gong by saying we need more JOBS, JOBS & JOBS?


